Why "Down Rounds" Are Becoming Normal Again, and Why That's Not Actually a Bad Thing
Say "down round" to a founder and watch their face instantly change. It's treated like a diagnosis. As proof that something went wrong under their watch. Most of the time, that's not what’s actually happening. It's just the story everyone agreed to tell during a very strange few years.
Here's what actually happened. During the 2021 run, valuations across almost every stage got detached from the fundamentals that would normally justify them. Capital was cheap, growth got rewarded almost no matter what the cost to produce it, and a huge number of companies raised rounds priced for a trajectory that assumed the party would keep going. It didn't. Rates went up, investors started asking about margins again instead of just growth curves, and a significant number of those valuations turned out to be snapshots of mood and not real assessments of the business underneath.
A down round is just what happens when the next raise reflects that correction. And if an entire cohort of companies got priced above what they were actually worth, at around the same time, for more or less the same market-wide reasons, then the company correcting its own price isn't the one that failed. The number failed a year or two ago, and everyone's only now being honest about it.
The stigma is what actually causes damage. We've watched founders who knew their last valuation was inflated, delay a necessary raise for months, burn runway they didn't have to spare, or accept genuinely bad terms just to avoid a lower number showing up on the cap table. That's optimizing for a headline instead of the company, and it turns a fixable pricing problem into a very significant one.
The founders who come out fine tend to separate two questions that get tangled together constantly: is the business actually working, and was the last number we agreed to actually real? Those questions are not synonymous. A company can be growing, retaining customers, genuinely improving, yet still need to reset its valuation because the last round priced in a funding environment that is not accurate anymore. Treating "our old number was wrong" as "we're failing" pushes founders toward decisions that are worse than the down round itself would have been.
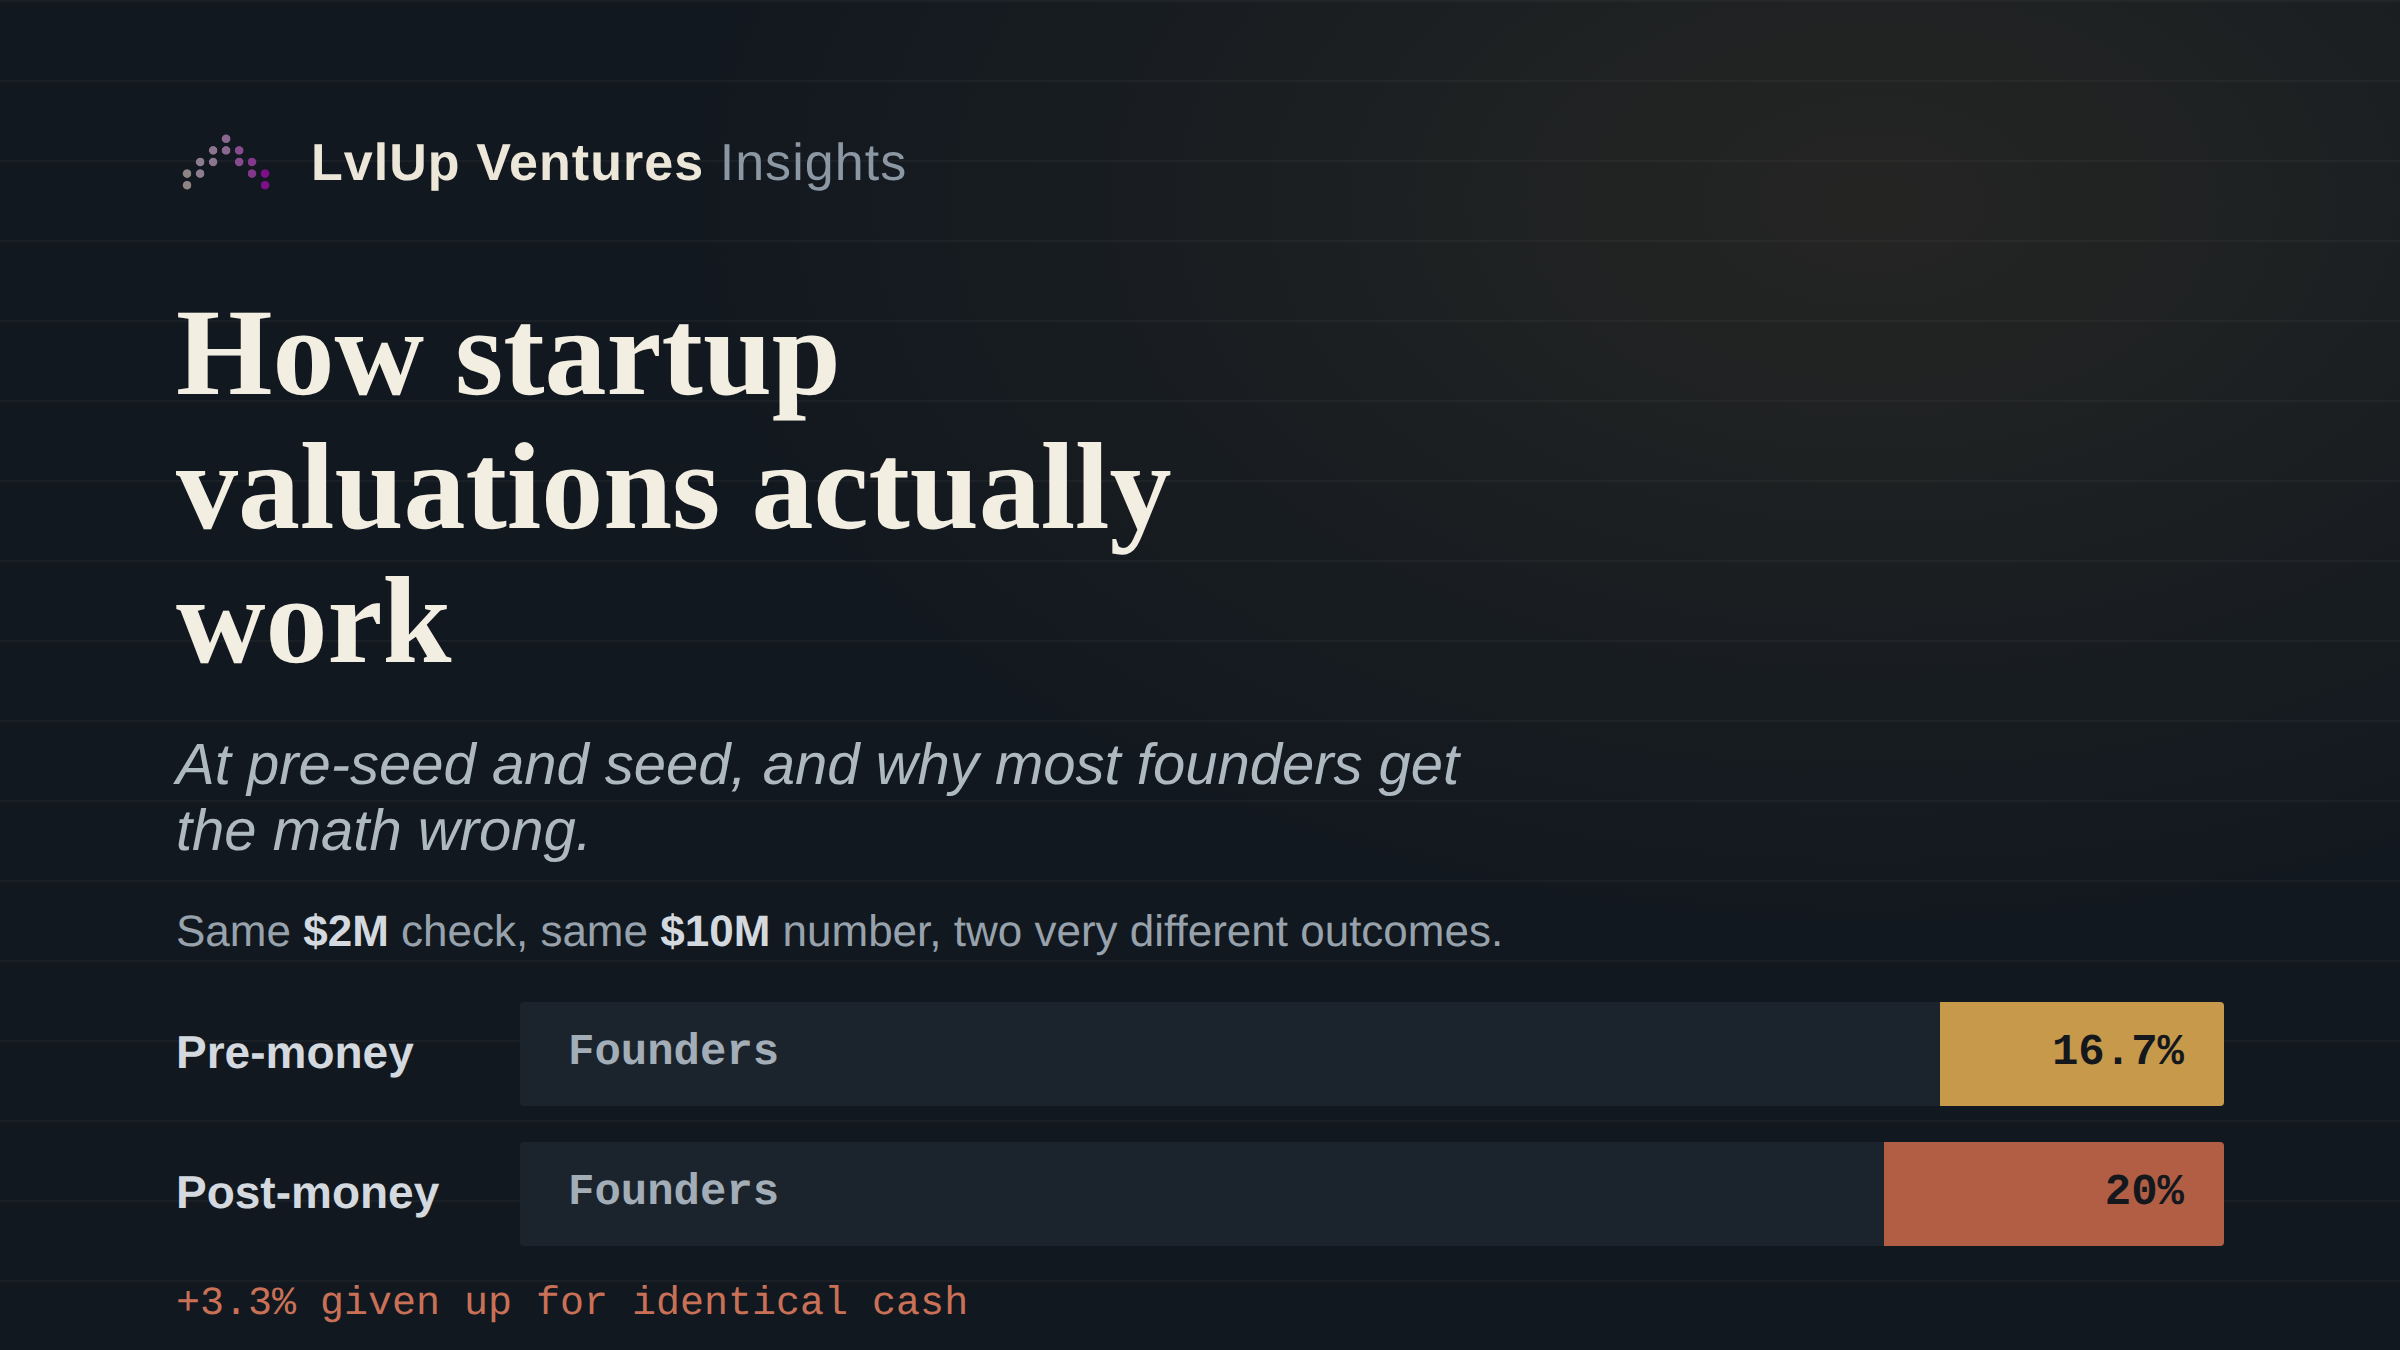
None of this is to wave away what a down round actually costs. Existing investors get diluted, sometimes hard, and depending on how the prior round's terms were written, anti-dilution provisions can shift real ownership away from founders and the option pool. Anyone walking into one of these should understand exactly how the cap table moves before signing.
But there's a difference between a company resetting its price because the market corrected, and a company resetting its price because it's actually dying, and the headline number looks identical in both cases. That distinction is getting lost, and it shouldn't.
If anything, a market where valuations only ever go up isn't the healthy version. That's a market where prices have stopped doing their actual job, which is reflecting information honestly in both directions. More down rounds right now isn't evidence that startups have gotten worse. It's evidence the market spent a couple of years mispricing risk in one direction and is finally doing the less comfortable work of pricing it accurately again.
The question worth asking, if you're a founder staring down this decision, isn't "how will this look?" It's simply: does this number reflect what the company is actually worth today, and does taking it keep you alive long enough to build toward a number that holds up next time? A founder who takes a clear-eyed down round to keep building is making a sharper call than one who avoids the correction and quietly runs the company into the ground, protecting a number that was never accurate in the first place.